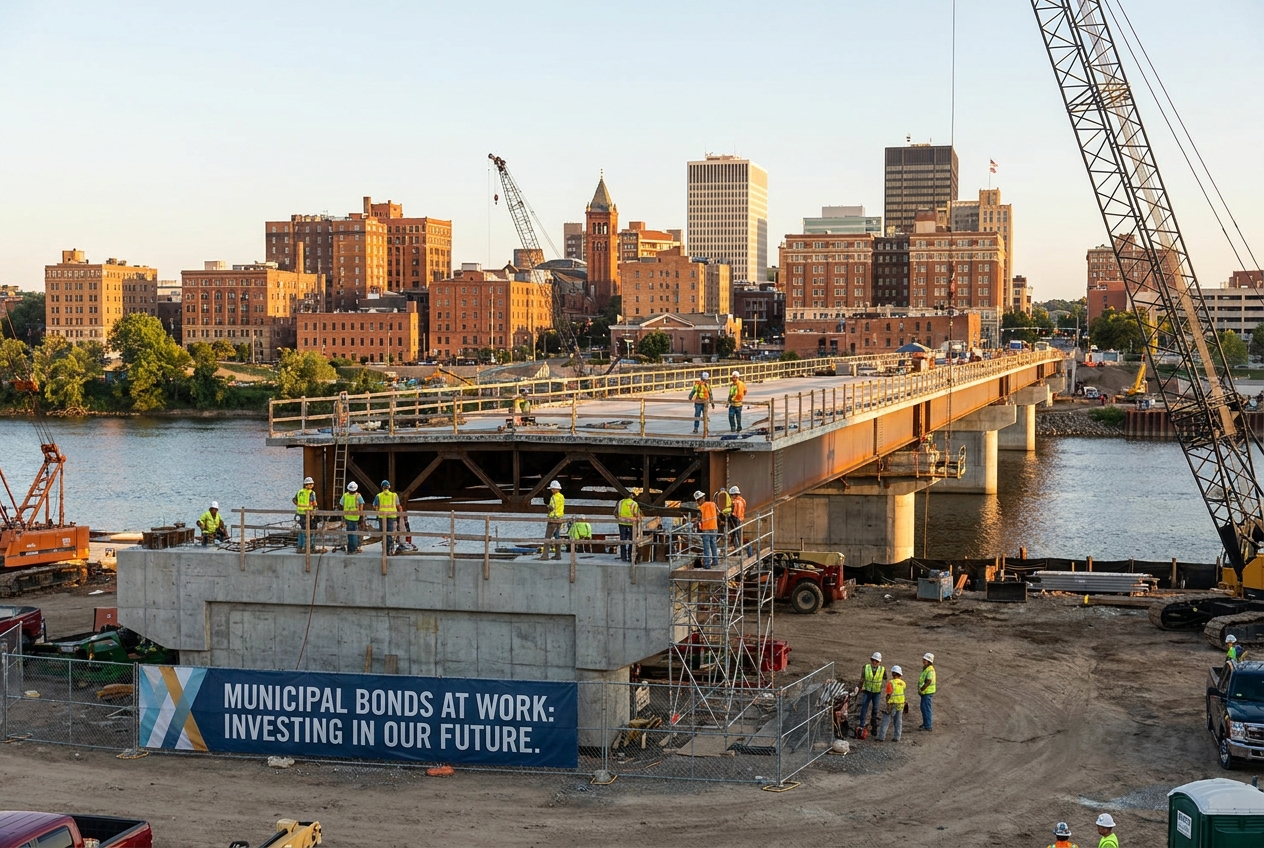
Regulatory spillover: Evidence from classifying municipal bonds as high-quality liquid assets
This working paper by Jacob Ott investigates the "regulatory spillover" effects caused by the Federal Reserve's 2014-2015 policy shift regarding the Liquidity Coverage Ratio (LCR). The LCR, a cornerstone of post-2008 Basel III banking supervision, requires banks to hold sufficient high-quality liquid assets (HQLA) to survive a 30-day stress period. Initially, U.S.
- Use cases, geography and tags
- Organizations that created, adopted or are mentioned
- Ecosystem position
- Link to the original asset
- Comments and reactions